THE BLOG
Your AI Strategy Is Already Obsolete
Stop automating the company you have. Start designing the company you need.
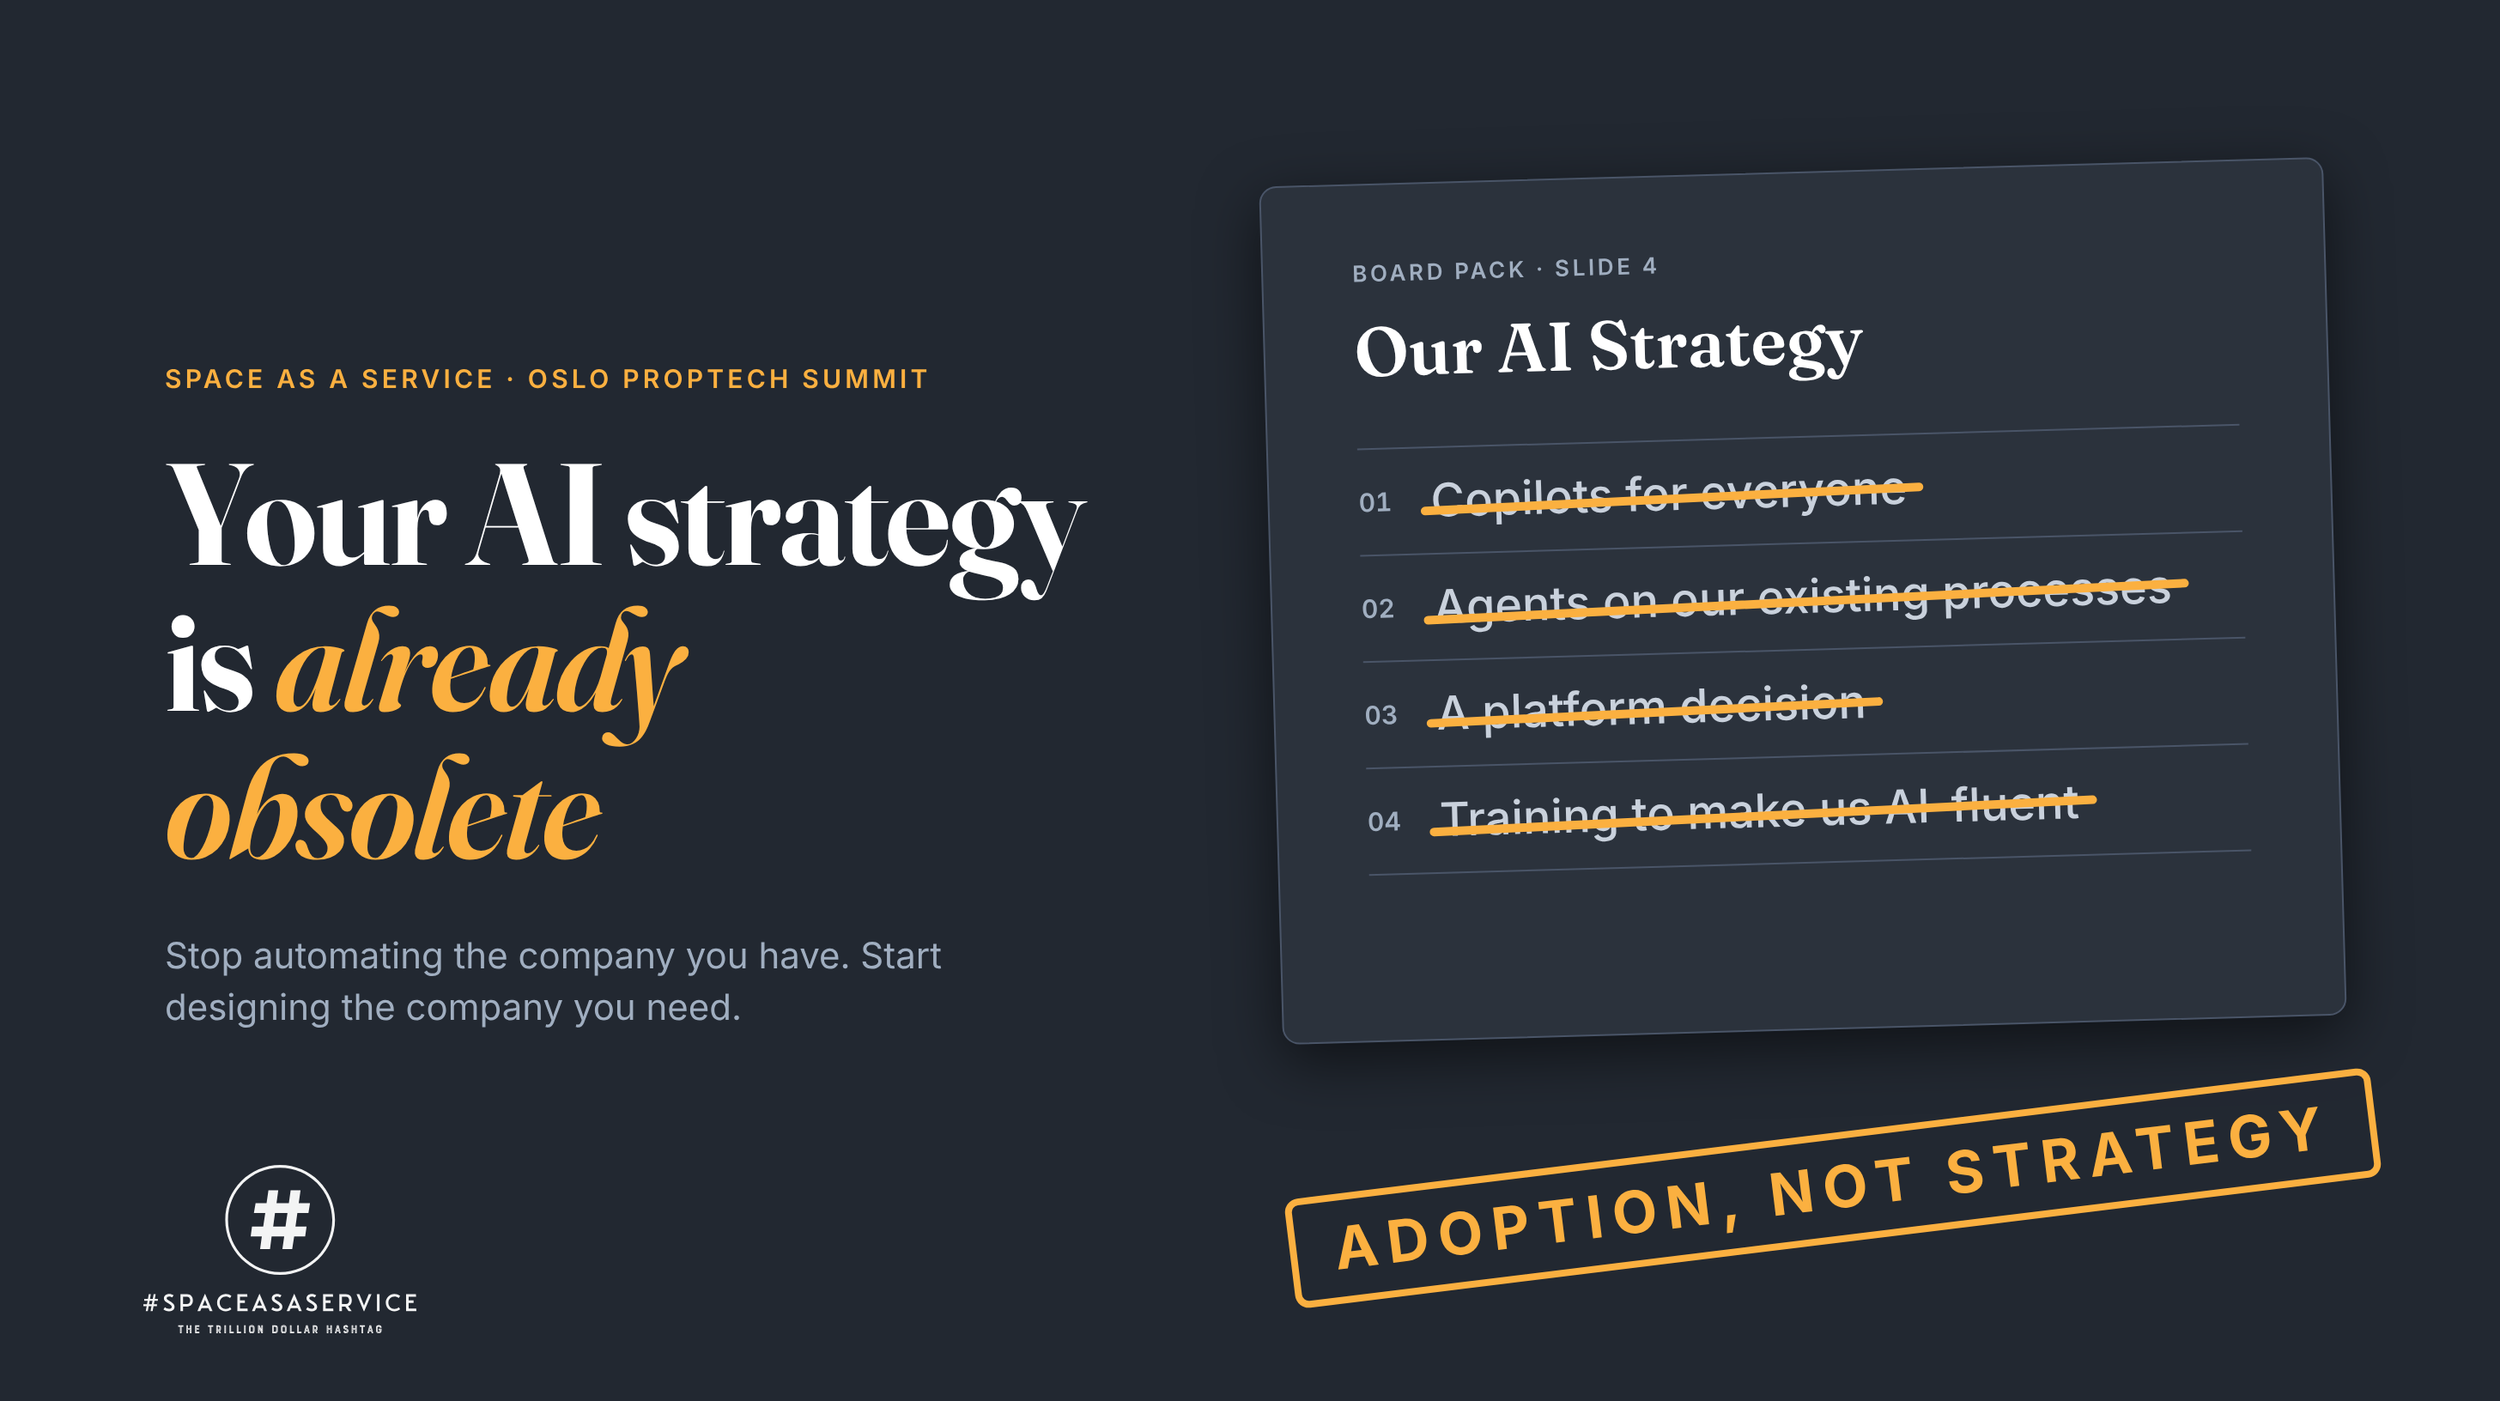
Last Wednesday I spoke at the Oslo PropTech Summit, a brilliant day in the Glasshallen. The talk took aim at the AI strategies most real estate companies have now written, and asked what should replace them. Below is the argument, developed in full.
Executive summary. Most CRE AI strategies are adoption programmes: copilots, agents on existing processes, a platform decision and training. They are useful, but they speed up the existing company without asking whether it is still the right shape. The alternative has three parts. Redesign like a founder: rebuild workflows, then the organisation, around what customers buy, so that every piece of work produces both a result and a more capable company. Score like an investor: ask separately whether a real buyer will pay and whether a better-placed player can take the position. Build to change: own a small, durable core and keep everything around it swappable, because nobody knows which future arrives.
YOUR AI STRATEGY, ON ONE SLIDE
I opened with a slide most of the room could have written. Four bullets:
Copilots for everyone
Agents on our existing processes
A decision on which platform to buy
Training to make us AI-fluent
Every item is defensible, several are necessary, and a company doing all four well is ahead of most of its peers. Put them together, though, and what you have is an adoption programme. It answers “how do we use AI?” and leaves alone the question a strategy has to answer: what will customers pay us for once the constraints that shaped our business have gone?
Efficiency programmes can be hard work to deliver, but they ask nothing of the business model. The org chart, the service promise and the fee basis all survive; the same work just takes fewer hours. And when every competitor can buy the same copilots and agents, using AI becomes the entry ticket. The edge has to come from somewhere else.
These strategies are obsolete, rather than merely incomplete, because they rest on a hidden premise: that the existing company is the right unit to optimise. That premise held while reading every document was expensive, analysis took weeks and expertise was scarce. Those were the constraints most CRE firms were built around, and they are going.
THE FIVE-YEAR QUESTION IS RIGHT
The better boards have started asking a different question: what does this company look like in five years? It is the right question, with three powerful sub-questions.
What will customers still pay for, once the commodity parts of the service cost almost nothing to produce?
Where does judgement matter, and until when? The second half matters as much as the first. As I argued in “Human Judgement Has a Timestamp“, the line between what needs a person and what doesn’t moves every few months.
What do you know that others don’t? Your data, your decision history, your relationships, your understanding of particular buildings and particular customers.
The danger lies in working backwards from a single answer. Nobody knows which five-year future will arrive. Pick one forecast, plan back from it, and you end up with a plan that only works if that forecast is right. Customer needs change far more slowly than technology does, so design around one of those, then test the design against several quite different futures and see where it breaks.
The core argument of the talk fits on three lines:
Redesign like a founder. Score like an investor. Build to change.
THE GROUND HAS MOVED
Before redesigning anything, be clear about who you are competing with, because the cast has changed. Five types of player now compete on the same ground:
Frontier labs: generic reasoning that improves every time the models do
Deployment companies: the repeatable, configurable middle, packaging that reasoning for common jobs
Incumbent systems: the systems of record beneath the work, now extending upwards into it
CRE operators: distinctive workflows built on their own context
Startups: the painful systems of work that customers can’t sensibly build alone
The fourth line changes most for a real estate audience. Your customer used to be the user of your product and its purchaser. Now they may also build their own alternative and compete for the value you hoped to capture. As the cost of building software collapses, the build-or-buy calculation that governed PropTech for fifteen years flips for a whole class of work. As CRE practitioners you have a new rule: build what is uniquely yours, buy what is not.
Every real estate firm is now both a PropTech customer and a PropTech.
Plenty of landlords will never write a line of code. All of them are now making a build-or-buy decision about their own workflows, and choosing to buy everything is a decision too. But the smart landlords are building. Vendors are being built around.
REDESIGN THE WORK
You can’t redesign a company by declaration. You redesign it one workflow at a time, taking specific workflows apart and putting them back together around what the customer actually buys. The method I use is RIRA.
Release. Which constraints has AI removed, and which has it added? Most firms only look at the first list.
Imagine. What was impossible? What was uneconomic? This is where you deliberately aim past efficiency. “How do we do this for less?” is rarely the useful question. “What could we now offer that we couldn’t before?” usually is.
Redesign. Rebundle tasks, roles and handoffs around what the customer buys, rather than around the order in which work used to have to happen.
Actualise. Put the redesigned workflow into operation: bounded, tested and recorded. Bounded means permissions, limits on what runs automatically, and clear rules for escalation. Tested means checking the workflow against real cases before trusting it, then measuring whether it works once live. Recorded means every judgement gets a source, a date and an owner.
Then you go round again. Actualise feeds back into Release, because the frontier moves and because outcomes tell you which of your assumptions were wrong. RIRA is a loop.
Release deserves more time than it usually gets. On the loosened side, AI has collapsed four costs that shaped CRE business models: the cost of reading every document, of producing analysis, of reaching expertise and of building software. Each of those once justified a layer of the org chart or a line in the fee.
The added constraints get less attention, and they are where firms get hurt:
Checking work you didn’t produce. Verification becomes a core skill, and a cost.
What your suppliers learn from you. Every tool you use is also observing how you work.
Accountability for decisions AI shaped. The committee still signs, and it now needs to know what it is signing.
A frontier that moves every few months. Any division of labour you settle on is provisional.
TWO MAPS, TWO JOBS
Once a workflow is taken apart, two maps help put it back together. They answer different questions. The first decides how each task should be performed and supervised. Place every task, rather than the whole workflow. I sort tasks on two axes: whether the work is cognition or plumbing, and whether its output is verifiable or hard to verify. That gives four zones.
Human-led strategic (cognition, hard to verify): asset strategy, the house view, negotiation. AI acts as challenger; a human decides.
The Karpathy Frontier (cognition, verifiable): benchmarking, scenario analysis, cost modelling. Named for Andrej Karpathy’s observation that AI most readily automates what can be verified. Evidence-based agents do the work; humans review it.
The Messy Middle (plumbing, hard to verify): supplier exceptions, occupier requests. Automate the core; people handle the exceptions.
High-ROI automation (plumbing, verifiable): lease data, critical dates, reconciliation. Straight-through processing, with checks.
The boundaries run through individual documents. Generating reminders from validated critical dates is verifiable plumbing. Deciding what a break clause actually requires of the tenant is interpretation: it carries legal risk and belongs with a person. The same lease sits in two zones depending on the task.
Every placement needs a date on it.
Better AI doesn’t automatically turn cognition into plumbing. What changes is how reliably the machine performs a task and how much human review it needs, and better evidence or a redesigned workflow can make an output easier to verify. A scenario model that needs a careful human check this autumn may need only a spot check by next summer. An undated placement never gets checked, and declines in value rapidly.
The second map decides what to buy, share or keep. Every workflow resolves into three bands. Plumbing is the mechanical work that is largely the same at every firm. Judgement is your method, your house view, your decisions and what happened next. Between them sits the overlap: systems of work every firm needs and none should build alone, such as market data, valuation conventions and shared definitions.
A WORKED EXAMPLE: SELL, HOLD OR REFURBISH?
To make this concrete, take a decision every owner faces: should we sell, hold or refurbish this asset?
Run the three bands over it:
Plumbing: lease events, cash flows, the arithmetic. A tool that does this, with its assumptions and workings open to inspection, is now cheap to build, for you and for every competitor.
The overlap: market data and valuation conventions. Mostly bought or shared, and rightly so.
Judgement: the owner’s objectives, the house assumptions, the questions that break the ranking, and what actually happened afterwards. Yours, if you learn from it.
The tool is copyable. What you learn with it can be yours alone.
That qualifier, if you learn from it, carries the whole argument. Owning your judgement and having good judgement are different things. A house view can preserve a firm’s biases as faithfully as its expertise, and a decade of confident hold recommendations proves nothing until someone checks how those assets actually performed. The advantage comes from the mechanism: write the assumptions down, compare them with outcomes, improve the method. A firm that does this learns faster than one that doesn’t, and it keeps what it learns. Either half on its own is worth far less.
The bigger prize lies in what the redesign lets you sell. Today an asset manager delivers asset strategy periodically: an annual business plan, a quarterly report, a paper when a lease event or an offer forces the question. The analysis is expensive to assemble, so it happens when it has to.
Once the evidence is kept current, the service can change shape. Decision support becomes continuous, with review triggered by the events that matter: a break notice, an unsolicited offer, a capex quote, a move in the debt markets. The same team can cover more assets without thinning the attention each one gets.
And it may open a market. It is my belief, argued in “From Boardroom Privilege To Baseline Utility“, that the larger opportunity lies with owners for whom serious asset strategy has always been uneconomic: the private owner with a handful of £5m buildings, the family office, the local authority. Cheaper production makes the service affordable. Whether it is good enough, and whether those owners will pay and can be reached at sensible cost, are viability questions to test.
That is a different company, with a different service promise, different coverage and potentially a different charging basis. Which is the point.
REDESIGN THE COMPANY
Follow the same asset-strategy workflow into the organisation and the existing structure starts to look odd.
Work. Today, information is assembled periodically for an investment paper. Redesigned, evidence is kept current and review is triggered when something material changes.
Roles. Today, analysts assemble, specialists contribute and seniors review. Redesigned, agents keep the numbers current while a small team challenges the assumptions and owns the decision.
Handoffs. Today, requests pass sequentially between teams. Redesigned, everyone works from shared evidence, with a named owner for each assumption.
Decision rights. Today, routine decisions wait for committee. Redesigned, set limits govern routine action, with escalation for consequential calls.
Learning. Today, papers are filed and lessons live in people’s heads. Redesigned, assumptions are compared with outcomes and the method is updated for the next team.
Junior analysts existed in such numbers because gathering and checking evidence was slow. Committees existed partly because evidence arrived in a lump and had to be judged in one sitting.
If the evidence can be kept current, why is the organisation still built around assembling it?
My answer, set out at length in “The Company After the Pyramid“, is small teams with explicit authority and shared capability:
Commitment Owner: authorised to decide, and answerable for it
Autonomous Professionals: own substantial parts of the work, improve the method and teach
Resident Learner: owns something that matters, such as the evidence behind one leasing assumption
System Architect: turns how we work into Skills, connections and tests a machine can run
Two of these deserve a note. In the old pyramid, juniors worked their way up by assembling things for other people. The Resident Learner instead owns a piece of evidence and answers for it. That brings responsibility, a feedback loop and direct exposure to consequences: when the leasing assumption proves wrong, it is theirs, and they see why. Those are the conditions under which judgement gets built. The System Architect role can start with one strong crossover person, someone who understands both the business and the tools and is often already on the payroll. As the spine grows, the role will grow with it.
Your position becomes the outcome you own and the authority you’ve earned.
What holds these teams together is the capability spine. I’ve written a full piece on how to build one, so briefly, it has six parts:
Trusted data and context, under your own definitions
Written, tested methods: your Skills and agents
Authorised connections to live systems
Evaluations that show where the human–machine line sits today
Decisions and outcomes, recorded
Relationship memory
Own the spine. Rent everything around it. Models, tools and suppliers sit on top and stay swappable, so next year’s better model plugs into the same spine.
Every consequential piece of work therefore has two outputs: value for the customer or the asset today, and a more capable company tomorrow.
Which raises an awkward question for nearly every incentive scheme in the industry. If you reward only this year’s production, who builds next year’s capability?
PROTECT THE POSITION
The three bands also tell you where to defend and where to cooperate, and the same map reads differently depending on which side of the table you sit.
A landlord or investor should rent the plumbing and keep it swappable. In the overlap, partner, and agree explicitly who keeps the learning. And own the judgement: write it down and record the outcomes.
A vendor should sell the plumbing beneath the customer’s edge. In the overlap, become the shared system while letting the customer keep its reasoning. And support judgement without owning it: the customer keeps its objectives and can see the reasoning behind any recommendation.
“Own the judgement” can sound like a ban on buying expertise. Specialist suppliers legitimately provide analytical judgement all the time: a valuer’s opinion, an energy model’s recommendation, a market forecast. What a company must keep is narrower: its objectives, its accountability for the decision, and the record of what it decided and what happened next. Buy all the analysis you like. Keep hold of the pen on why you chose.
The test for every supplier relationship comes down to one question:
Is the thing you depend on also the thing capturing what makes you you?
I’ve called this the toll and the amputation. A toll you can pay. An amputation you can’t undo. A supplier charging for plumbing is levying a toll. A supplier whose system quietly accumulates your methods, your assumptions and your decision history, in a form you can’t take with you, is doing something else entirely.
The smartest firms on both sides are designing for the same overlap. Pool the learning about common work. Keep the learning about your judgement.
SCORE LIKE AN INVESTOR
Whether you are deciding what to build internally, which vendor to back or where your own business is exposed, two questions need asking, and they need scoring separately. This is the logic behind my weekly Build/Back analyses.
Viability: is there a real, reachable buyer whose pain matters?
Owner: does one role feel the pain and sign for it?
Trigger: is there a clock forcing a decision?
Budget: does it displace a cost they resent, or create enough value to justify new spending?
Distribution: is there a realistic route to them?
Price: will they pay enough to cover delivery?
Defensibility: can a better-placed player take or absorb this position?
The incumbents: can the systems already in place easily extend into it?
The models: can a general-purpose AI easily replicate it?
The customer: can an in-house team easily build its own?
The third threat is the new one, and the one most PropTech pitch decks still skip. Survive all three and the position is hard to take. Survive none and it is exposed, whatever the pitch deck says.
Cross the two answers and you get four positions:
Build or back: a real buyer with owned pain, and a position that survives all three threats. This earns serious commitment and further diligence. It doesn’t settle the price, the valuation or whether the team can execute.
Defensible but stranded: clever, hard to copy and nobody’s budget.
A distribution play, clock ticking: real revenue, no moat. The returns can be perfectly worthwhile; what they lack is durability. Fine to harvest, dangerous to value as though it will last.
Don’t: no moat and no buyer. The kindest finding of all, because it stops anyone wasting another penny.
Never average the two scores. A 90 for defensibility and a 20 for viability averages to 55 and describes a stranded asset. And date every score, for the same reason you date every task placement: the models move, and a position that looked safe in the spring may not be by Christmas.
BUILD TO CHANGE
We asked for flexible buildings for twenty years and got open plan.
We are about to ask for flexible AI and get a single-vendor platform.
In both cases the flexibility on offer was the freedom to do one thing in slightly different ways. Real flexibility is the ability to change what the thing is for, at a cost you can bear.
So for every commitment, whether a model, a data store, a method, a supplier contract or a team design, ask four questions:
What change must it accommodate?
How quickly?
At what cost?
With how much disruption?
Then decide which options are worth paying to keep open. Optionality always costs something: abstraction layers, portable data, second suppliers. The point is to choose which flexibility you buy, rather than discovering three years in that you bought none.
Lego works because the studs are standard: anyone’s brick fits anyone else’s. Your studs are shared definitions, interfaces and permissions: what a “lease event” means in your data, how your systems talk to each other, who and what is allowed to do what. Standardise those and everything above them becomes replaceable. Your methods and your learning are what you build with them, and those are what you keep.
WHAT TO DECIDE ON MONDAY
An AI strategy isn’t an IT strategy. It’s a company strategy. Redesign the work. Redesign the company. Build for a future none of us can predict.
That takes decisions only the leadership of a company can make. Three would get you started:
Which customer outcome do you redesign first? Pick one where the product itself could change: sold differently, or to more people, as well as done faster.
Who has the authority to change the work? Redesign stalls when the person running the pilot can’t touch roles, decision rights or the fee basis. Give someone that authority, and make them answerable for it.
Who makes sure the company learns? Someone has to own the spine: the recorded assumptions, the outcomes, the updated methods.
That last one matters most. If learning is everybody’s job, it will be nobody’s.
And a company that doesn’t learn will find whatever strategy it writes next is already obsolete too.
What Work Happens in This Building?
Portfolio Optimisation in an AI Future
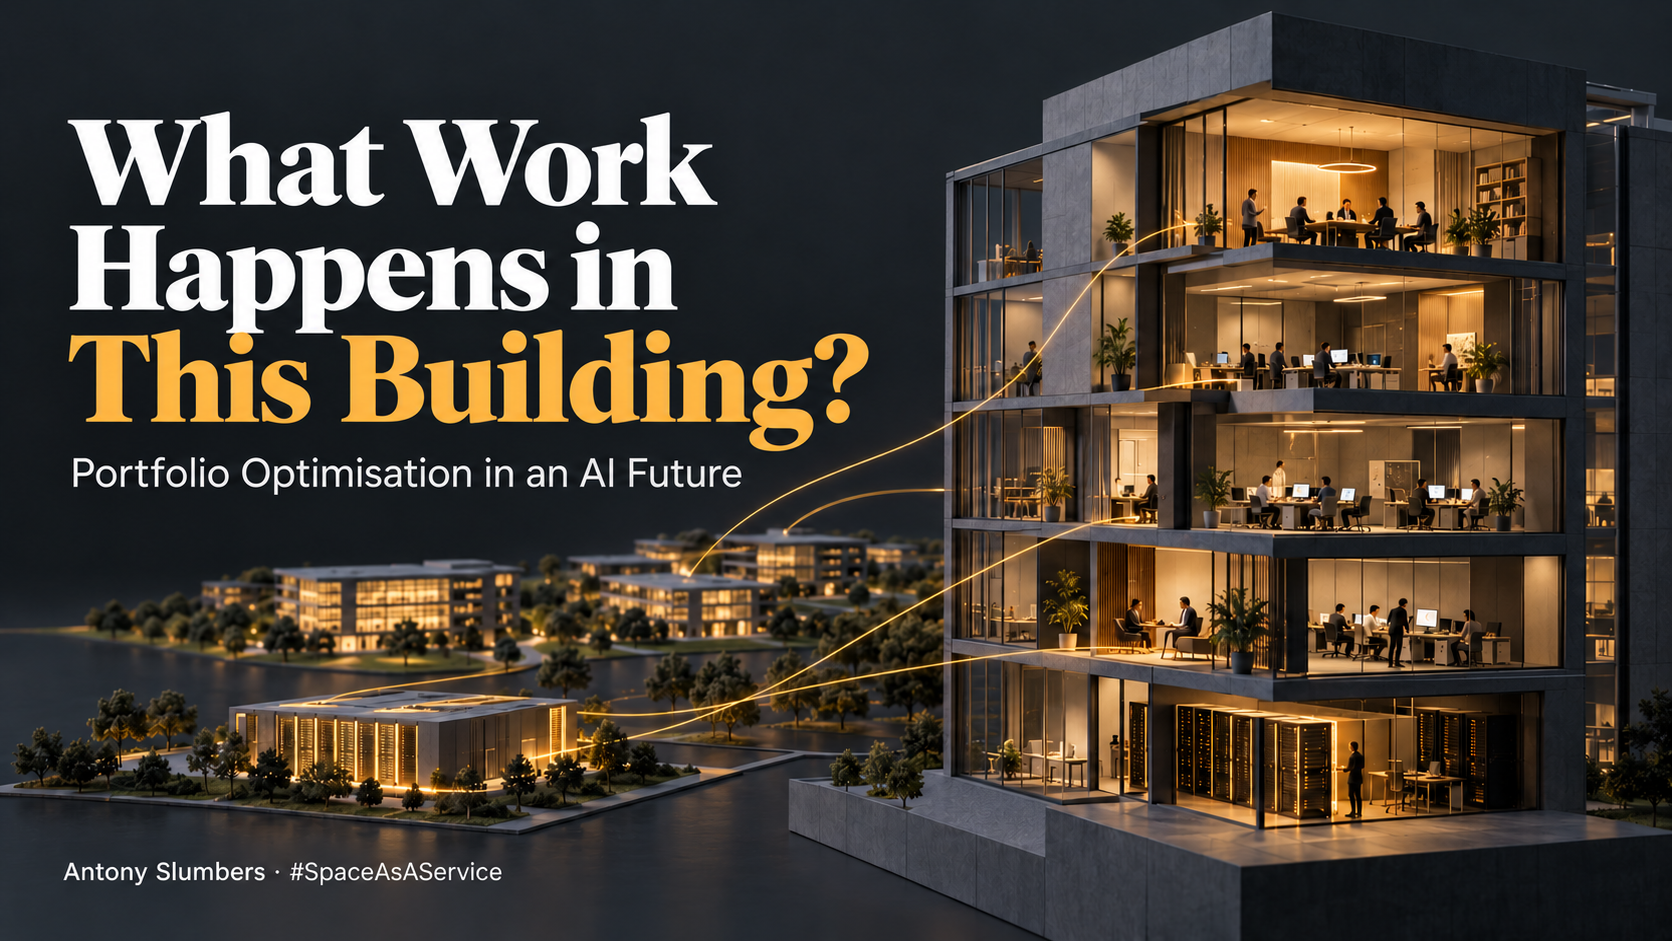
Every lease, fit-out and location decision assumes an answer to one question: what work happens in this building? AI is changing that answer faster than our planning models can see, and a frontier model can now read much of it from public sources.
Last Thursday I gave the closing keynote at CoreNet Global UK’s Future Focus in London, the last session before drinks. I told the room I had recently been with a major landlord, talking about why it needs to understand its occupiers in a far more granular way. At CoreNet I was on the other side of the table, but the message was the same. Occupiers need to understand the work they do just as precisely, because their leases probably assume a pattern of work that is already shifting.
EXECUTIVE SUMMARY
Space demand has long been forecast from headcount growth. AI weakens that link, because output no longer tracks the number of people, so the past relationship between growth, headcount and space becomes a poor guide to the future. What matters more is the mix of work: which tasks need a person, which need a particular place, and which can move to a capability centre in Bengaluru or into software altogether. Different kinds of work will settle in different geographies, and UK cities start from very different positions: the City of London has about six managerial and business-professional jobs for every administrative one, against fewer than two in most big regional cities. Two test runs on real buildings, BT in Birmingham and Meta in London, show that public sources now reveal a great deal about an occupier, and that the facts which decide the outcome are mostly already in the landlord’s own files. All of this matters today. In three to five years it will have real bite.
THE BROKEN EQUATION
Most occupier space forecasts, and most landlord underwriting, still start from three terms: how many people, how many of them share each desk, and how much space each desk needs. The best occupiers now plan around activities and peak days as well, but the forecast usually begins with projected headcount. We have argued about the last two terms for a decade. Hybrid working moved desk sharing; densification moved the space per desk.
AI breaks the first term. Output no longer tracks headcount.
Which means the same AI gain can produce opposite space answers. Take a 500-person firm in 60,000 sq ft at a constant 120 sq ft a head, give it 40% more output per person over five years, and change only how fast its business grows. If output stands still, it needs about 360 people and 29% less space. If output grows 10%, about 390 people and a fifth less. If output doubles, about 710 people and 43% more. Same AI gain, same building, same planning team: growth decides the answer, and growth mostly comes from the sector you are in. With a 40% productivity gain, a firm has to grow its output by 40% just to stand still on space. The napkin maths is deliberately crude; the spread is the point.
The aggregate numbers may not show this for a while. National vacancy and take-up figures can look reasonably calm, because the change happens inside buildings before it shows up between them, and because much of it appears as missing absorption: growth that never becomes occupancy here, because it landed somewhere else or in software. Vacancy tells you what left. It cannot tell you what never arrived.
The market will look fine. Your building might not.
WORK HAS A SHAPE
So the question becomes: what work is actually done in a building, and how exposed is each kind?
The lens I’ve been using sorts tasks on two axes. One is whether a task is plumbing (moving, checking and reconciling information) or cognition (interpreting, analysing, deciding). The other is how verifiable the output is: can you tell, cheaply, whether it was done right? Verifiability decides how fast AI arrives, far more than whether the work feels routine or clever.
That gives four kinds of work, and they map neatly onto how most organisations are actually staffed:
High-ROI automation (verifiable plumbing): reconciliations, reporting, rule-based processing. Most of what we’d call routine processing and administration. Increasingly done by machines.
The messy middle (hard-to-verify plumbing): exceptions, supplier issues, occupier requests. Automate the core; people resolve what falls out of it.
The Karpathy frontier (verifiable cognition): analysis, benchmarking, modelling, much technical and engineering work. Evidence-based agents with human review.
Human-led strategic (hard-to-verify cognition): relationships, negotiation, capital allocation, accountability. Leadership and client-facing work. AI as challenger; a human decides and signs.
David Autor and Neil Thompson’s work on expertise shows why the task mix matters more than any headline ‘exposure’ score. Between 1980 and 2018, US employment of bookkeeping and accounting clerks fell by about a third while their real wages rose by about 39%: the routine work went and what remained was harder. Stock and inventory clerks went the other way, with employment up 175% and real wages down 13%: the expert work went and the job got easier. Similar exposure, opposite outcomes, for the people and for the floorplate.
The direction of travel is clear to me. Organisations will unbundle their workflows into tasks, route each task to whoever or whatever does it best, and rebundle the result into much smaller teams. Many of the people in those teams will spend their days directing agents rather than producing the work themselves: what Microsoft’s 2025 Work Trend Index calls the ‘agent boss’. Fewer rows of production desks. More rooms where people review, argue and decide.
WORK HAS A POSTCODE
Different kinds of work will have different geographic preferences, and AI is redrawing that map faster than the industry is pricing in.
Offshoring is old hat. Back offices have been heading to Glasgow, Belfast, Kraków and Bengaluru for decades. What has changed is the kind of work that moves. Zinnov and Nasscom count 2,117 global capability centres (GCCs) in India as of March 2026, employing 2.36 million people. 44% of them now sit at the two most mature levels, where the Indian centre owns products, platforms and IP end to end, or runs AI-led operations under global executive mandates. These are the places where firms build and run the machinery of their business.
That changes who the competition is. GCCs now provide a home for work that used to go to Manhattan rather than Milwaukee, or London rather than Liverpool: the analytics, engineering, product and risk work that firms once kept close to head office. They are competing with the first-tier city, and that is where much of the missing absorption comes from. Growth that would once have filled another floor in London turns up in Bengaluru instead. GCCs are exposed too. The work they are taking is often the most verifiable work a firm does, so many will industrialise it, automate it and shrink into smaller, more technical control rooms. Expect the hub to compress as well.
JPMorgan shows the shape of the new system. In November 2025 it announced a 3 million sq ft tower at Canary Wharffor up to 12,000 staff as its European headquarters. Weeks later it signed for a build-to-suit campus in Powai, Mumbai, reported at around 2 million sq ft, for back-office and technology functions. One firm, two very different buildings, each designed around a different kind of work.
Put the four kinds of work on a map and a pattern emerges. These are likely concentrations, with plenty of overlap: a big GCC can hold all four, and much focused work in any of them happens at home, as a rhythm rather than a place.
Human-led strategic work lives in the HQ, in prime locations near clients, regulators and other firms. Prime gets more important and more elitist, but it is used intermittently, sized for the peaks of commitment, learning and client moments rather than for daily attendance. The catch is learning: if the junior analysis that used to train future partners moves to Bengaluru or into software, the HQ has to make room for apprenticeship on purpose, with places for review, critique and teaching used by the whole team.
The messy middle lives in the hub: GCCs, nearshore centres and regional hubs, where exception handling at scale needs depth of talent at a sensible cost.
The Karpathy frontier splits. The machine is built and run in the hub, often by very capable engineering teams at scale, and increasingly owned there: Zinnov’s Portfolio Hubs hold products and platforms end to end. What stays at the HQ is the commitment: capital, regulatory accountability and the signature. Top-end work can move to a GCC.
High-ROI automation lives in the machine. It has a geography (power, compute, data centres) but no desks.
It is my belief that prime HQ locations will matter more, but will house a narrower and more elite slice of the firm: commitment work, clients and learning, used intermittently. Much of their growth will leak to the GCCs. The clearest losers will be regional office markets built on processing and the messy middle, which have long competed with offshoring for that work and now face automation as well. That is a hypothesis, and I set out below what would prove it wrong.
THE MAP AT HOME
UK cities start from very different positions. The ONS Annual Population Survey counts jobs by where people work, by occupation. I compared two groups: corporate managers and directors plus business, media and public service professionals (the lawyers, accountants, consultants and analysts), and administrative occupations. They are rough proxies for commitment work and processing; each of those jobs is itself a bundle of tasks. Pooling the three years to March 2026 to smooth out sampling noise:
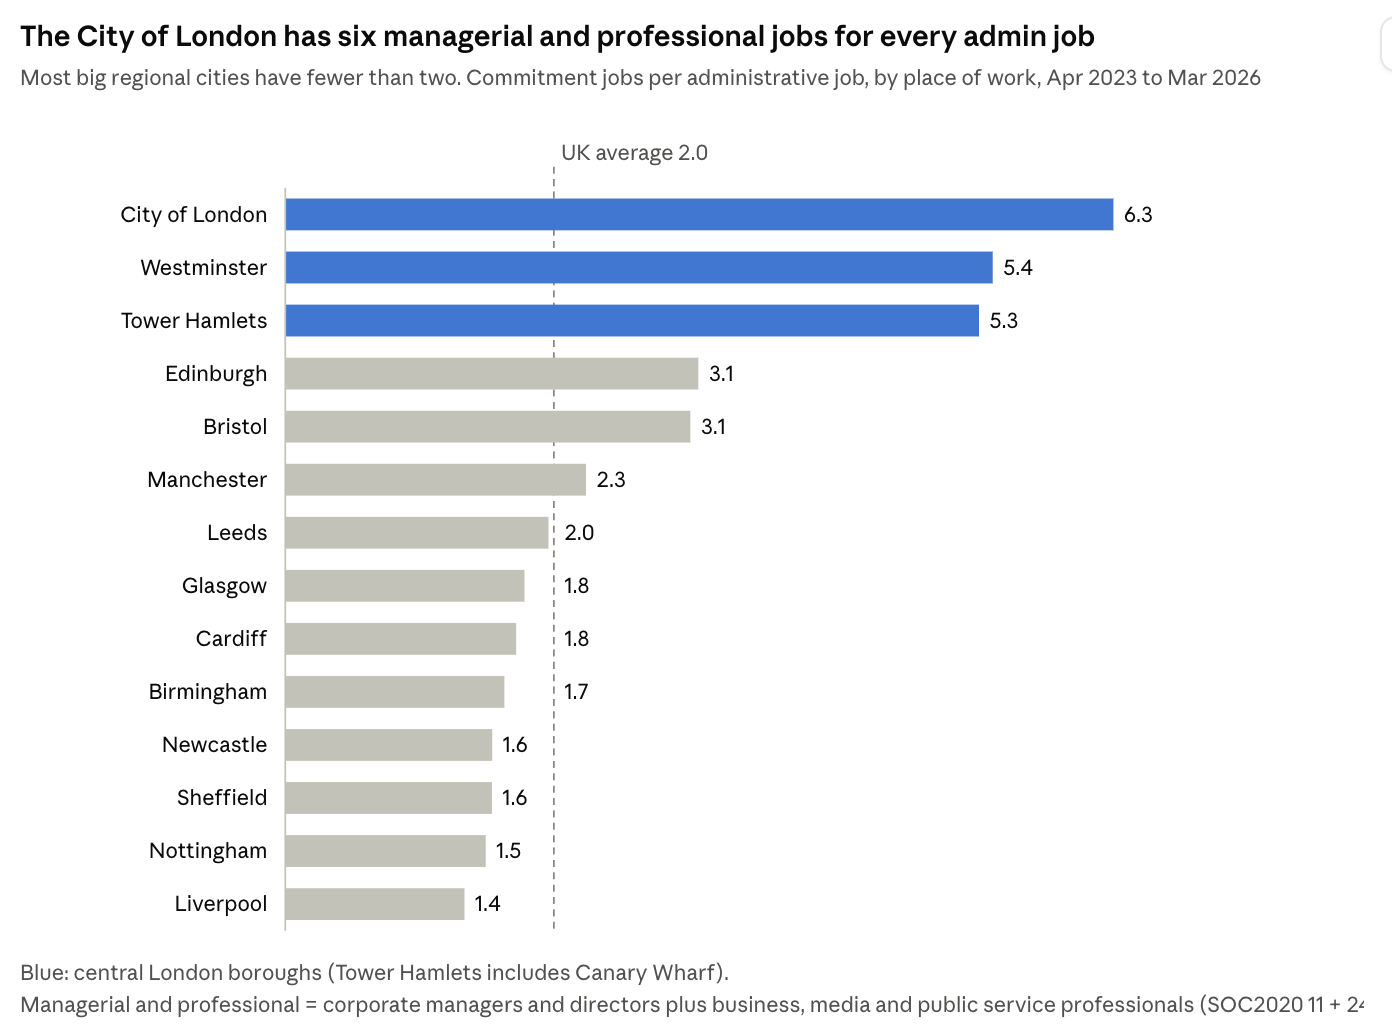
In the City of London there are about six of the first group for every administrative job; in Westminster and Tower Hamlets, just over five. Edinburgh and Bristol sit at about three, above the UK average of two, which suggests a regional city can build a different mix. The gap is driven by the top of that fraction more than the bottom. Administrative jobs are between 6% and 10% of workplace jobs almost everywhere. What really sets central London apart is the managerial and professional share: 36% of jobs in the City and 43% in Tower Hamlets, against 12–21% in the big regional cities. None of this makes London safe. Much of the work in those professional groups (junior accountancy, compliance, routine legal work) is highly verifiable. To my mind the regions are more exposed on processing, and London on the Karpathy frontier.
Two cautions. These are survey estimates, so the order among similar regional cities is within the margin of error; the gap between central London and the regions is not (it holds even at the edges of the ONS confidence intervals). And occupation is a proxy: part of any city’s administrative workforce sits in the NHS, councils and universities, where AI gains are more likely to show up as more output than as fewer seats. This is a snapshot of today’s mix, and it says nothing yet about AI sorting work. What it shows is where the exposure sits. In central London most jobs are office jobs, and a large share of those are commitment work. In the big regional cities office work is a smaller share of all jobs, and less of it is commitment work, so more of their office base is the kind of work that can move to a GCC or into software.
TWO BUILDINGS, PUBLIC SOURCES ONLY
Last week I built a skill that does this analysis for a specific occupier in a specific building. It reads the occupier’s public exhaust: job postings and where they are located, Companies House accounts, results and strategy statements, agents’ listings, licensing and planning applications, local press. It separates documented fact from inference, estimates which kinds of work are likely to sit in the building, ties that to the lease clock, and lists what would need confirming on site. Two runs are worth describing.
BT at Three Snowhill, Birmingham. BT signed a 20-year lease on 283,000 sq ft in 2020, then Birmingham’s largest office letting, for a hub designed for up to 3,500 people. Floors 7 and 8 are now being marketed by JLL as ‘The BT space’: up to 46,540 sq ft, fitted, about 16% of BT’s holding. Group-wide, BT targets 75,000–80,000 total labour by March 2030, down from 108,000, and its results presentation linked the cuts to “greater use of AI and automated processes”. In 2022, 1,800 of BT Digital’s 2,800 new roles, 64%, went to Bengaluru and Gurugram. None of that is a Birmingham forecast on its own. It matters because Three Snowhill houses digital and corporate functions, and BT advertises such roles for Bristol, Birmingham or London alike. On the floors directly below BT, National Highways does similar office-based planning and administrative work, but as a public body whose demand is set by the road network it is more likely to take AI gains as more output than as fewer seats. Same building, similar work, and quite possibly different trajectories.
Meta at Rathbone Square, London. Meta’s name is on 15-year leases with no breaks, running to 24 March 2032, and its covenant is very strong. But Meta left in 2024. The people on the floors are monday.com, with about 80,600 sq ft on the top three floors for an expected 300-plus staff (roughly 267 sq ft each) before it cut about a fifth of its global workforce in July 2026; an events operator that has applied for a licence for 750 people on the ground and lower levels; and an unnamed party under offer for the rest. The lease terms, including the fact that the leases sit inside the Landlord and Tenant Act 1954 (which gives business tenants a statutory right to renew), came from the agent’s listing. The events operator came from a local news report on a licensing application. For the owner, the rent is secure to 2032; what has changed is the size of the reletting problem it inherits then, and that depends on how each deal was papered.
In neither building did AI cause what is happening. Hybrid working (BT’s average attendance was 1.7 days a week in late 2024) and pre-AI cost cutting emptied those floors. AI is the amplifier: the reason BT’s 2030 cuts could go deeper than planned, and the backdrop to monday.com’s restructure around its own AI product.
That finding strengthens the case for granularity. ‘AI empties offices’ gets both the mechanism and the timing wrong. The granular view tells you something different in each building. At Three Snowhill it shows which functions are exposed and roughly when. At Rathbone Square it shows that the name on the lease is not who is on the floors, and that the 2032 question turns on subtenants nobody underwrote.
THE DATA YOU ALREADY OWN
Both runs also tested a belief I’ve held for a while: that much of the company-level data this industry pays for is worth less than people think. Fresh transaction evidence and verified building data are another matter.
Working from public sources alone, a frontier model rebuilt the company-level picture in each case in surprising depth: headcount trends, function mix, hiring geography, strategy, subtenants, lease terms. Much of what data vendors sell at that level is being commoditised in front of us.
What the public record cannot see is the building at floor level. The facts that would decide each outcome are of a different kind. For BT: whether floors 7 and 8 are a sublet or a surrender, the break dates, and which of its remaining floors are running at base load. For Meta: whether each deal was an assignment or a sublease, and whether the subleases are protected under the 1954 Act. Every one of those sits in the landlord’s lease and licence files or its building management data. The Meta report notes that the owner’s licence files would settle the two biggest unknowns in an afternoon.
The scarce asset, then, is the data you already sit on and rarely use, joined to public intelligence that anyone can now assemble. Floors running at base load on the energy data are, in my view, one of the earliest warnings of a hand-back, and a signal worth testing alongside attendance and lease events. (One firm rule on method: this works at the level of company, building, floor and department. Never individuals.)
Occupiers face the same opportunity from the other side. Instrument your own work properly, with methods written down and decisions and outcomes recorded, and you get as a by-product the evidence of activity that badge data never gave you. If your landlord can tell your business what space it needs before you can, you’re left negotiating the price.
WHAT CHANGES IN THE PORTFOLIO
The point of all this is better decisions. Once you know what work sits in your buildings, four of them look different:
Renewals. Test the occupier’s future functional requirement before assuming today’s area rolls forward.
Capital expenditure. Separate a shrinking requirement from a building-quality problem before committing refurbishment money. A better building will not refill floors whose work has moved to Bengaluru.
Acquisitions. Underwrite occupation and reletting risk alongside contracted income and covenant. Rathbone Square’s income is about as secure as West End income gets; its 2032 position is a separate question.
Concentration. Look for exposure to the same kind of work across tenants in apparently different sectors. A bank’s operations team and a telco’s finance function can carry much the same risk.
For occupiers the list is shorter: size the HQ for commitment and the peaks, and match lease length to how settled the work inside it is.
SLOWLY, THEN SUDDENLY
Slowly, then suddenly. That is roughly how I expect this to play out.
All of this matters today. The portfolio decisions being made this year (leases signed, hubs chosen, fit-outs specified) already assume an answer to what work happens where. But the real bite comes in three to five years, as the unbundling of workflows reaches the core of how firms operate and the GCCs finish moving up the stack. A ten- or fifteen-year lease signed now will run through several generations of models.
I want to be precise about what is evidence and what is belief. That different work wants different places is observable today. That a granular, work-level understanding of occupiers will become the decisive input to portfolio strategy is a hypothesis, and I’m happy to be judged on it over that three-to-five-year horizon. It would be wrong if:
knowing the work mix does not improve forecasts of space change at lease events beyond what headcount, sector, attendance and existing property data already explain;
GCCs plateau at delivery work instead of taking ownership of core functions;
return-to-office mandates keep floors full regardless of what people do on them.
I don’t expect any of those to hold. But each can be watched, and I will.
For occupiers, portfolio optimisation in an AI future starts with knowing what your organisation actually does, and what it is becoming. For landlords, it starts with knowing the same about your occupiers. Both are now possible. Very few are doing either.
The most important asset in your portfolio isn’t a building. It’s knowing what happens inside one.
Sources
Antony Slumbers, The New Geography of Work: HQ, Hub, Home and Machine in the age of AI, CoreNet Global UK Future Focus, 15 October 2026 (scenario table from AI and Office Space Demand, February 2026)
BT Group at Three Snowhill: Occupier Functional Audit and Meta at Rathbone Square: Occupier Functional Audit, 14 October 2026 (full source lists inside each)
ONS Annual Population Survey, workplace analysis via Nomis, dataset NM_100_1, table T09b (SOC2020 sub-major groups), Apr 2023–Mar 2026
Zinnov–Nasscom, GCC Landscape in India 2026, data as of March 2026
David Autor and Neil Thompson, Expertise, NBER Working Paper 33941, footnote 5
Construction Enquirer, JPMorgan Canary Wharf tower, 27 Nov 2025; Brookfield Q4 2025 letter to shareholders (JPMorgan Powai build-to-suit and Canary Wharf HQ)
Show Me the Incentive
AI can lift NOI across real estate, most directly where landlords run the operation themselves. Whether it does depends less on the technology than on what your people believe will happen to them.
On Friday I was asked how to persuade a board to fund AI redesign work. It sent me back to a deck I took to boards in 2023, called ‘Generative AI: Preparedness’. Rereading it was instructive and a little uncomfortable. Most of it was sensible at the time. Much of it has expired. And the section on people, which turns out to be the one that decides everything, was the weakest of the lot.
Executive summary
AI-driven productivity flows into NOI and gets capitalised, which makes it a capital argument for the board, potentially worth far more than a few salaries. The effect is clearest in operational real estate, and it reaches any landlord that manages its own buildings through voids, retention and service. The listed operators are already taking that gain, mostly as lower payroll. That creates the real obstacle: the people whose work has to change are afraid of the change, and new Gallup data shows the heaviest AI users are the most worried of all. The fix is incentives: a deal, written down before you start, on who gets the gain and how the change happens. Firms that settle it will compound; firms that don’t will pay for tools their people quietly route around.
WHAT I TOLD BOARDS IN 2023
The deck had six headings:
fostering a culture of innovation
laying the data foundation
harnessing tacit knowledge
AI literacy
pilot projects with ROI measurement
navigating a dynamic landscape.
Some of it holds up. Leaders should use AI visibly. Tacit knowledge is where the value sits. Outside expertise helps. Strategy needs revisiting.
The people section reads worse. It proposed innovation hubs, quarterly challenges, certificates and a ‘Knowledge Contributor of the Month’. It promised that education and demonstrated value would ‘guarantee universal buy-in’. Nothing in it asked the question every employee was silently asking: what happens to me?
A confession about this piece, too. What follows will date. In August I argued that ‘human judgement has a timestamp‘, and the same applies to advice. Treat what follows as a reading taken in October 2026, to be retaken.
THE EDGE MOVED
Four pieces of 2023 advice show how fast the ‘jagged edge’ of AI capability moves. Each was reasonable at the time.
Data foundation first. In 2023 the received wisdom was that AI needed tidy, structured data, and the models of the day could hold far less in view at once, so cleaning data first made sense. Today’s models handle large volumes of messy documents, emails and spreadsheets well, and a two-year data programme before anything else is a recipe for unnecessary delay.
What still matters is data quality where an agent acts. When a system takes a step on a rent roll or an arrears ledger, a wrong number gets executed, where in 2023 it would only have been reported. So dealing with data has become easier, but the stakes have risen.
Knowledge-capture sessions. Extracting what experts know was right then and is right now. What changed is the output. In 2023 it produced documents for people to read, and the expert usually lost ownership of the knowledge the moment it was written down. Now it produces ‘Skills’: the expert’s method, encoded so a system can run it. That raises the personal stakes for the expert considerably, which is why the rest of this piece is about the deal they are offered.
Pilots measured in time saved. Tools in 2023 were assistants that sped up tasks, so time saved was the obvious metric. Agents can now take bounded steps in a workflow, with checks. The measure that matters is the workflow’s outcome: days to let, renewals retained, arrears collected.
Literacy workshops. Capability now moves several times a year, so a one-off course decays almost as fast as my deck did. Training has to be continuous, delivered in the work, on the firm’s own workflows, and tied to redesigning them.
Fluency on its own is table stakes: any competitor can train or hire its way to parity. The advantage comes from what trained people then redesign and build.
The lesson is easy to state and hard to act on.
An AI plan without a date on it is a depreciating asset.
LABOUR IS NOI
When I started on this piece, my instinct was that labour savings make a weak argument in real estate. Real estate firms are asset-heavy and people-light, so a board hearing ‘productivity’ hears ‘a few salaries’ and shrugs.
That instinct was wrong for a large and growing part of the market. In operational real estate (such as build-to-rent, student housing, hotels, flex, senior living) site labour sits above the NOI line. Every pound of recurring operating cost removed, net of the software, the oversight and any slippage in service, is a pound of NOI, and NOI is capitalised. At a 5% yield, £1 of NOI is worth roughly £20 of value. That is illustrative arithmetic, and it is a capital argument. Boards understand capital.
The listed operators are already making it. AvalonBay in the US told investors in April that it is on track for $55m of annual incremental NOI from its operating initiatives by the end of this year, with further AI deployment and further optimisation of neighbourhood and centralised staffing next, on the way to an $80m target. The usual caveat applies: much of the model is centralisation that predates large language models, and AvalonBay doesn’t say how much of the NOI is down to AI.
Equity Residential’s March investor update is more explicit about people. It says its innovation programme delivered $55m of NOI between 2020 and 2025 alongside a headcount reduction of roughly 20%, and it expects a further $25m and roughly 10% from a second phase running to 2028, with AI leasing, AI service optimisation and AI-supported collections among the initiatives. NexPoint reported payroll down 4.3% in the first quarter, which it attributed to its centralised operating model and AI-enhanced leasing.
In the UK, Grainger is targeting EBITDA margin expansion from 56% to 60% by FY29 from its operating platform, and its chief executive has argued that Grainger is more likely to benefit from AI in its operations because of its data. Unite expects nearly £7m of annual operating cost savings from its technology platform upgrade. Both figures cover platform efficiency in general, and both show where operators expect the next margin to come from.
Two qualifications. First, structure decides who keeps the saving, and for an owner of a mixed, multi-let estate the levers move rather than disappear. Savings on recoverable costs mostly pass through the service charge to occupiers, and in hotels and senior living a management agreement splits them between owner and operator. What stays with the landlord is everything else: shorter voids, faster lettings, better renewals, fewer arrears, and a property team that can look after more buildings and more occupiers without growing. A well-run, competitive service charge is part of what an occupier pays rent for. On a long-hold estate, all of that compounds.
Second, the gain won’t stay exceptional. EliseAI says one in six US apartments now uses its software. It is my belief that when everyone runs the same leasing AI, the saving becomes the market’s baseline, and buyers will underwrite it. An asset run the old way will then be priced against an operating model it doesn’t have.
So the board case is strong. Look at how the gain is being reported, though: as payroll and headcount.
And that is where the problem starts.
YOUR HEAVIEST AI USERS ARE THE MOST AFRAID
In September Gallup published a study drawing on four waves of US panel data from 2023 to early 2026. Workers who use AI daily or several times a week were more than twice as likely to fear their job will be eliminated within five years as those who use it occasionally. Familiarity brought no reassurance. That fear costs money: as a worker’s displacement anxiety rose, their engagement fell, burnout rose and they became more likely to look for another job.
The people who lean in are the people most afraid of where they think leaning in leads.
What made the difference was management. Workers who felt respected, and felt their organisation cared about their wellbeing, showed a much weaker link between heavy AI use and fear of losing their job. Gallup reports this as an association, tracked in the same people over time, and its advice to leaders is to connect AI to team capability rather than headcount efficiency.
Meanwhile, people hide what they do. Deloitte’s survey of 25,000 UK workers, published last month, found that 31% of those using generative AI at work do so without their employer’s knowledge, around half have had no formal training, and 64% of weekly users worry their managers will think AI can do their jobs. When leaning in looks risky, people lean in privately. The firm then carries the data risk and can’t systematically capture the learning.
This piece rests on a concession. Some of these fears are correct. In a firm with a static portfolio, AI-driven productivity will mean fewer roles over time. Telling people otherwise will be found out, and quickly, and the cost will be every promise you make afterwards.
So the useful question for a board is who gets the gain, and how the change happens.
SHOW ME THE INCENTIVE
Charlie Munger’s favourite illustration of incentives, from his 1995 Harvard talk on the psychology of human misjudgment, was Federal Express. The whole system depended on moving every package through a central hub overnight, and the night shift kept failing to finish on time. FedEx tried moral suasion and everything else it could think of. Then someone noticed the night shift was paid by the hour, so a slow night paid better than a fast one. FedEx started paying by the shift, and the system began to work. It is the story behind the line he is usually quoted as saying: show me the incentive, and I’ll show you the outcome.
Your AI programme has a night shift. If the visible consequence of working faster is fewer colleagues, or your own role disappearing, you have built FedEx’s hourly rate into your transformation. No amount of ‘culture of innovation’ will outrun it. I proposed certificates in 2023. Munger would have laughed.
One warning before the remedy. FedEx’s output was easy to see: planes loaded by dawn. Outcomes in real estate lag and get muddied by markets, so pay tied crudely to them invites gaming. Measure tickets closed and you get tickets closed, solved or otherwise. Every outcome measure needs a quality check beside it.
With that caveat, here is the deal I would propose. It has six parts, and it should be written down before any redesign starts.
Say what happens to capacity. A growing firm can offer the bigger pie: more units, more services and better retention, run by the same headcount. I’ve argued before (’From Boardroom Privilege To Baseline Utility‘) that AI’s real prize is the demand it makes economic for the first time: services, customers and assets that were never worth serving at the old cost. For an operator that might mean resident services, smaller assets or third-party management. Redesign can create that growth, but someone still has to go and win it, and the extra capacity only protects jobs where they do. A firm with a static portfolio has to make a different offer, and make it honestly: change through attrition and redeployment, first claim on the new roles, and a real share of the gain. Real means specific: a team bonus paid from verified net improvement in the workflow, protected time to build new skills, a defined route into a more valuable role, and funded transition support where redeployment isn’t possible. Promise anything except ‘no change’.
Give decision rights to whoever redesigns the work. The person who rebuilds a workflow should own the rebuilt version. Progression should come from expanding decision rights, as I argued in ‘The Company After the Pyramid‘.
Pay on observable workflow outcomes, with checks. Days to let alongside the quality of the let. Resolution time alongside requests reopened. Arrears collected alongside tenancies lost.
Make skill authorship a career asset. Skills can be drafted from documents and examples, but only the specialist can validate the method, its limits and where it should be used, so they have to be central to designing the skills that run it. A skill complements the expert and substitutes for the expert’s repetition: once built, it handles the routine cases without them. That is the point of it, and pretending otherwise insults everyone’s intelligence. The firm will own the skill as intellectual property, so the author’s ownership has to mean authority: they decide how the workflow changes, approve revisions and can challenge what it produces. Name the author, and count authorship in promotion and pay, judged on use and quality, never on volume. Art history has a 400-year-old vocabulary for this kind of attribution (’workshop of’, ‘attributed to’): graduated authorship under a named hand.
Keep the library alive. Someone has to curate the skills, date them and review them as the edge moves, and that review sends the work back to the specialists. This is the System Architect role I described in ‘The Company After the Pyramid‘. It is a loop, never an event.
Stop punishing disclosure, and train continuously. Provide sanctioned tools, reward people for showing how they use them, and keep training. Continuous training is the firm’s side of the bargain: we keep investing in you, you help redesign the work, and you share in what it earns.
One test covers all six. Would someone still think this a fair deal if their current role eventually disappeared? If the answer depends entirely on keeping the job, the deal needs more work.
The deal also has a precondition: managers and executives have to be paid for it too. Gallup’s finding is that managers are the buffer, so their incentives come first, particularly in the middle layer whose job has been routing information. And if the executive committee is still rewarded for cutting headcount while managers promise people a share of the gain, staff will believe the executives’ incentives, and they will be right to.
THE RIGHT SIDE OF CHANGE
Now the individual, because the firm can only do half of this.
The change is coming whatever any of us thinks of it. What’s different now is how much agency a single person has to show what they can add. Every week I put a CRE or PropTech company through a Build/Back analysis, using Skills I designed and maintain myself, and my arguments get pressure-tested by a virtual board before they reach you. A few years ago that would have needed a research team and a fair amount of budget. The caveat matters for anyone doing this inside a firm: a tool one person built in a day, on a personal account, holding tenant data, is a liability until it is sanctioned and maintained.
For a domain specialist, leaning in now has a concrete form: designing and curating the skills that run your own method. That is a far stronger position than waiting to see whose method gets encoded.
Is it a moat? Only as a rate of learning. The fluency you acquired last year is worth less every month, and if everyone leans in, nobody is ahead. The durable advantage is the habit of keeping up, combined with domain knowledge competitors can’t download: being full stack, in CRE and in AI. The firm supplies the continuous training. The individual supplies the habit.
That habit only survives in a firm that makes leaning in safe. Which brings us back to the deal.
I should declare an interest. I run a training programme and help firms redesign workflows, so I benefit when you lean in. Weigh this piece accordingly.
BEFORE YOU START
For the board paper, six inputs, all settled before any build begins:
The NOI line you’re targeting, and roughly how much.
One workflow that’s already hurting.
An owner who carries the P&L for it.
A baseline, measured before anything changes. Without one, nothing can be proved later.
The people deal, written down and announced, including what people get if their role goes.
A staged budget with gates and kill criteria, covering continuous training as well as build.
The last question a board will ask is what it’s actually paying to build. My short answer, which I’ll be developing in a series of masterclasses at Cityscape in Riyadh next month: you can rent the brain and most of the harness. You can’t rent your context, your method or your accountability.
WHO GETS THE GAIN?
A prediction to hold me to. Within two years, a buyer’s underwriting on a UK build-to-rent or student housing asset will explicitly assume an AI-enabled operating cost base, and the seller’s legacy model will be priced against it.
When that happens, the operators who settled the people question early will have the cost base, the skills and the staff who built them. The others will have bought the same tools and watched their people work around them.
Get the incentives wrong and you buy tools. Get them right and you get capacity. Write the deal down and you get a firm that keeps learning.
So: who gets the gain in your firm, and do your people know the answer yet?
Design for the Moments That Need a Room
What AI-first work means for the workplace, the building and the business model.
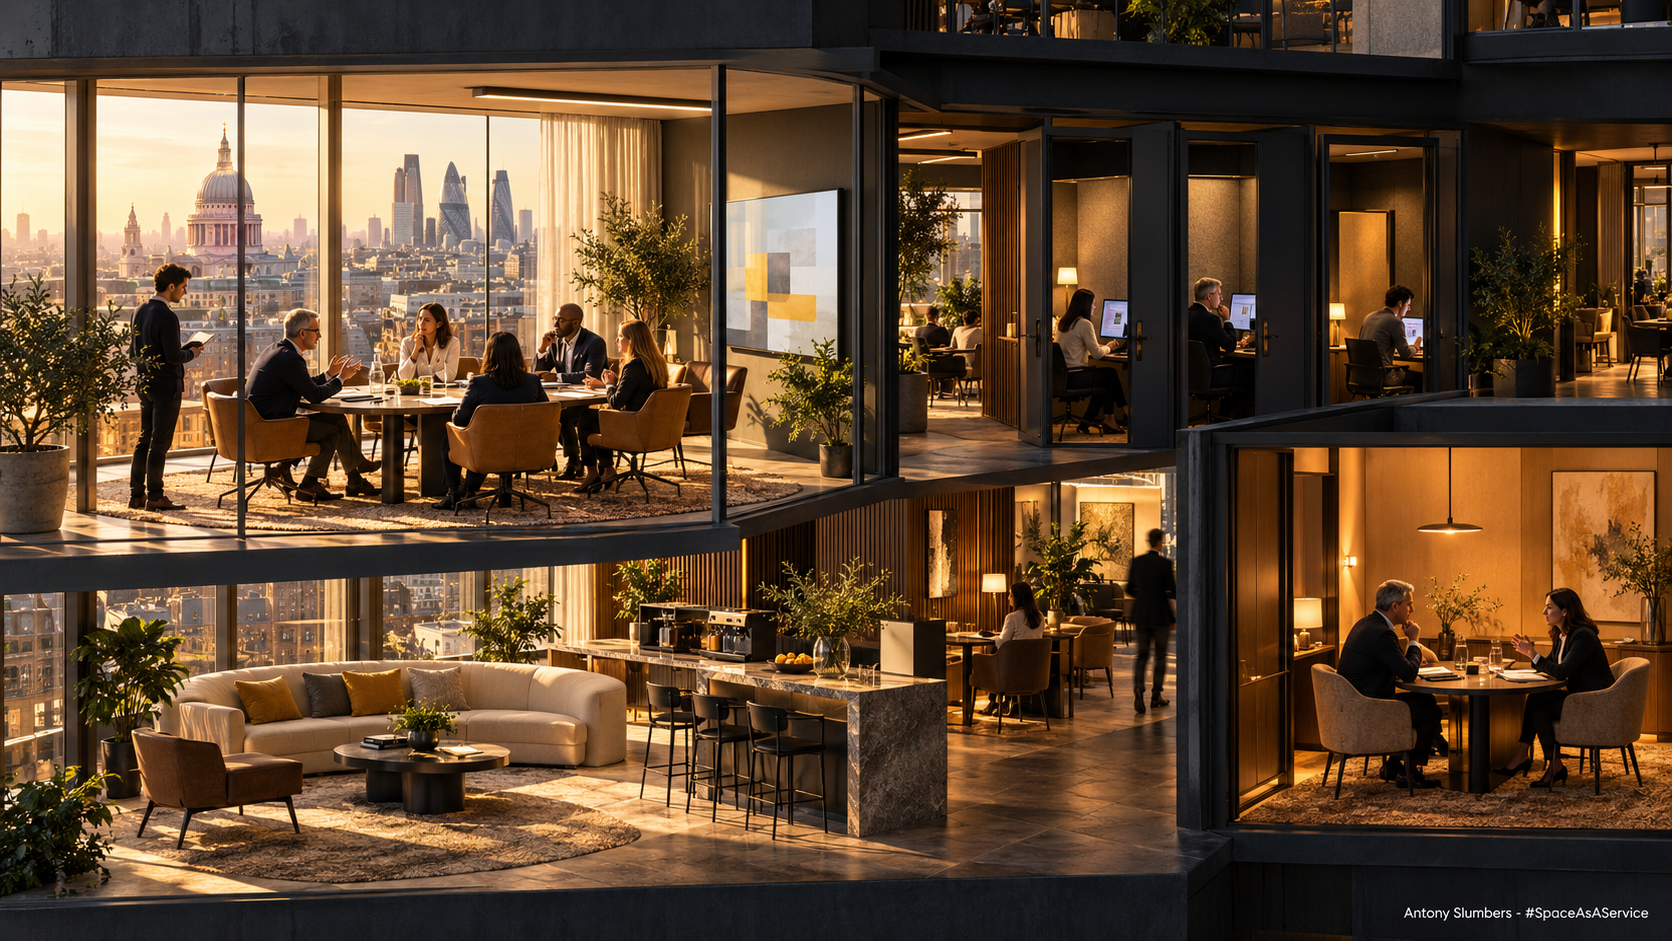
A friend asked in a WhatsApp group recently whether anyone was thinking about the physical office in the age of AI. My recent slides talked about smaller, more purposeful teams, and he wanted to know how those teams would actually use the space. It’s the right question, and it deserves a proper answer, because most of what gets written on it starts with trivia, the furniture. So this is my answer. It’s also a chance to look back at a piece I wrote two years ago, Real Estate as Maven, which argued that buildings themselves should actively help the people in them, and to consider what I got right and wrong.
Executive summary
AI is going to change why you go to the office, and the layouts should, and will, follow from that. Most of the tasks offices were built for, and much of what we call judgement, can now be done anywhere, increasingly by AI. What stays valuable in person is social (but more specific than the nebulous term ‘collaboration’): making commitments to each other, agreeing what a group wants, bringing on junior staff, and meeting people who think differently. Design for those moments and you get fewer desks, many more rooms for meeting and hosting, some rooms where everything is recorded and some where nothing is, and small private rooms for working with AI in between. For most companies, rooms like that would sit empty much of the week. So at the top of the market the answer is a building shared by many companies and many uses, run like a hotel by people whose job is to book, prepare and host them.
START AT THE RIGHT END
Most of what gets written about the office in the age of AI starts with the kit: which screens go in which meeting rooms, which sensors in which ceilings. That’s the wrong end. The layout should follow from why people come in at all, and AI changes that answer more than anything else.
A quick word on terms, because in real estate ‘agents’ means something else entirely. When I say agents here, I mean AI agents: software that carries out a piece of work on your behalf, such as reconciling a rent roll, drafting a report or running a set of scenarios, and comes back to you with the result.
Those agents can do the work anywhere. Drafting, analysing, modelling, summarising, checking: the tasks offices were built to house travel perfectly. And more and more of your time will go on supervising that work.
We’re already partway there. In the week to 28 September 2026, US office attendance averaged 54.7% of pre-2020 levels and peaked on the Tuesday at 65.3% (Kastle), and Mondays and Fridays typically run at around half the midweek peak (Analysis Atlas). The UK tells a similar story: Remit Consulting’s tracking hit a record 44.1% of office capacity in late January 2026, against a pre-pandemic norm of 60–80% (Remit Consulting). People already come in on particular days, for particular reasons. AI will sharpen that. What are those reasons?
The usual answer is that we’ll come together for judgement. I’d be careful with that. In Human Judgement Has A Timestamp I broke judgement into three parts: prediction (working out what’s likely to happen), preference (deciding what we want) and commitment (binding ourselves to a course of action). Prediction is the part AI is getting good at, and fast. Build your office strategy on that part of judgement and you’re building on the part that’s leaving. The other two are where the office’s future lies.
So what’s left?
WHY WE’LL STILL TURN UP
What keeps its value is social by nature. I see four reasons to come in. Three of them will last, because AI can’t do them at all. The fourth depends on how AI develops.
Commitment. In the late seventeenth century, merchants and ship owners met in Edward Lloyd’s coffee house to size each other up and put their names to risks. The principle still holds. AI can forecast, but nobody can hold it to a promise. Deals, mandates, investment committees and client relationships all rest on people binding themselves to each other. And as fake voices and video get cheap and convincing, turning up in person becomes the one signal that can’t be faked.
Presence is proof.
It proves who was there, and that they said it to each other’s faces. Whether they keep their word is another matter, but that’s true of any promise.
Deciding what we want. An AI can rank your options against a goal. It has no standing to set the goals for a group of people. Strategy, standards and the trade-offs between colleagues get negotiated, sometimes politically and often emotionally, and people only accept the outcome if they took part in reaching it. You’ll know that from any team you’ve ever run.
Formation. This is how juniors become professionals. They build trust, shared standards and a sense of who they are by being around the people they’ll work with. When Microsoft studied its own staff after the switch to remote work, people’s working networks became more static and siloed, with fewer links between groups (Yang et al., Nature Human Behaviour). That’s a problem we cannot ignore.
Variety. People who think differently, from different firms and disciplines, come up with ideas a single team won’t. This is the reason that depends on AI. Ask the leading AI tools the same open question and, on the evidence so far, you increasingly get similar answers. That makes real difference between people scarcer, and so more valuable. If the models become more varied, this reason weakens. The other three still stand.
That does not mean any of these four still need a physical space to convene. You already agree mandates, settle strategy and keep in touch with colleagues over video, and plenty of commitments between people who already trust each other will carry on that way. Being in the room earns the journey in particular situations:
- when the other side is unfamiliar
- when the decision is contested
- when the stakes are high and trust is thin
- when someone is learning by watching.
Those are the moments that need presence. Everything else can travel.
Two other popular reasons are weaker than they look. The first is pooling expertise: getting the people who know different things into one room. AI already does much of that. In a 776-person experiment at Procter & Gamble, individuals working with AI did as well as teams working without it on product-development tasks (Dell’Acqua et al., The Cybernetic Teammate). The second is building and managing AI agents, which is mostly solo work at a screen. The part that needs a room is agreeing, as a team, what good work looks like, which takes us back to deciding what we want.
A DAY IN THE AI-FIRST OFFICE
My friend’s real question was what all this means for the people who work there. So let me make it concrete with an illustrative day, around 2030, for an asset manager at a real estate investment firm. It’s made up, but every part of it follows from the four reasons above.
She comes in on Tuesday because three things that need her in a room are happening on Tuesday. Overnight, her AI agents have reconciled the rent roll, drafted the quarterly investor update and run three scenarios on a refinancing.
At nine, her team of six meets in their own room, around a large shared screen. They go through what the agents produced, agree what’s good enough and what isn’t, and change the instructions for next time. That’s the team deciding what it wants. A graduate sits in on all of it.
At half past ten she spends an hour in a small private room with a door, talking her agents through a different structure for the refinancing. She mostly works with them by voice now, and the numbers are confidential, so an open-plan desk is no use to her.
At half twelve she has lunch with a possible joint-venture partner from another firm, on a floor shared by all the companies in the building. The building’s management team introduced them, because they knew both firms were looking at the same kind of asset.
At two she meets the lender in a room where nothing is recorded: no microphones, no transcripts, phones left outside. They agree heads of terms. Before anyone leaves, they write the terms out by hand, read them back and both initial the page. Then they shake on it.
At half three she takes the graduate through how the negotiation went: what she conceded, why, and how she read the other side.
She leaves at half four. The follow-ups agreed at the nine o’clock meeting have already gone to the right people and their agents. On Wednesday she works from home.
Now picture your own week, and the days you genuinely need to be in. Those are the days this office is for.
THE BRIEF
Turn her Tuesday into a design brief and you get something very different from today’s office.
Fewer desks, far more rooms for meeting. Rooms for small teams, proper rooms for deals and clients, and spaces you’d be proud to host people in.
Large shared screens where a team reviews what its agents have produced and agrees what good looks like. The agents do the work; the room is where people check it and set the standard.
Small private rooms for working with agents, next to the team rooms. People will bunch their in-person moments into one day, and in between they’ll work with their agents, mostly by talking to them. That needs a door, not a desk.
Good sound insulation everywhere. Once people talk to their agents all day, open plan stops working for anything confidential.
Rooms that are either fully on or fully off. Some capture everything said; some capture nothing. More on this in a moment.
Rooms that prepare themselves. Before a meeting, the room’s systems pull together the relevant emails, documents and notes from last time. During it, they take notes and capture who agreed to do what. Afterwards, the follow-ups go to the right people and their agents. Most of the pieces exist already: Microsoft’s Copilot prepares a pre-meeting briefing from related emails, documents and past meeting notes (Microsoft), and its Facilitator agent takes notes and captures action points in physical meeting rooms (Microsoft). What’s missing is joining them up and making them standard.
Space for juniors where they can see and hear how seniors work, plus training the building can run for graduates from all its occupiers, such as sessions and mentoring with senior people from other firms, the kind of programme a ten-person company could never run on its own.
Shared floors where people from different companies meet, with dining, events and introductions made on purpose by the people running the building.
Everything bookable and easy to rearrange. You come in for the things that need a room. Nobody needs another bank of hot desks sitting empty on a Friday.
If you run a single company, look down that list and ask how many of those rooms you could keep busy. The shared floors need people from outside your firm by definition. The learning works better with them. And unless you’re very large, most of those rooms would sit empty much of the week. That’s where the property argument starts, after two more design points.
ON AND OFF
One design rule deserves its own section, because I think it’ll become the most distinctive feature of the AI-age office. Every room should be either fully on or fully off, and everyone in it should know which.
A fully on room captures the conversation. AI is listening, what’s said is transcribed, the room is prepared before people arrive and the follow-ups go out as they leave. It’s where teams work with their agents and review what they’ve produced.
A fully off room captures nothing that’s said. No microphones, no cameras, phones left outside. It’s where deals are negotiated, investment committees deliberate, decisions about people get made, and anything that needs candour happens.
Off still means documented. Before anyone leaves, the people in the room write down what they agreed, by hand, read it back and initial it: heads of terms, a committee’s decision and its reasons, an agreed next step. The rule is simple. Nothing said leaves the room, only what the people in it choose to write down together. That’s how deals were recorded for centuries, and writing the terms out together is itself part of making the commitment.
The real problem is the half-on room, which is where most offices are drifting. Transcription and AI assistants are optional, used inconsistently and sometimes quietly running. Nobody’s sure what’s being kept, so nobody quite says what they think. You’ve probably sat in that meeting already.
I expect the off room to become something people pay for, for three reasons:
Scarcity. When every meeting is transcribed by default, a room guaranteed to record nothing becomes the rare thing.
Candour. People say different things when nothing is kept, and candour is what real commitments are built on.
Proof. With voices and video easy to fake, being in the room together is the strongest evidence of who agreed to what.
The guarantee has to be real: equipment that physically can’t record, a clear sign on the door, and someone everyone trusts to make sure. In a building shared by several companies, that someone is whoever runs the building.
WHAT SITS NEXT TO WHAT
A layout is about proportions, and about what sits next to what: who walks past whom, and how long it takes to get from one room to the next. Four principles follow from her day.
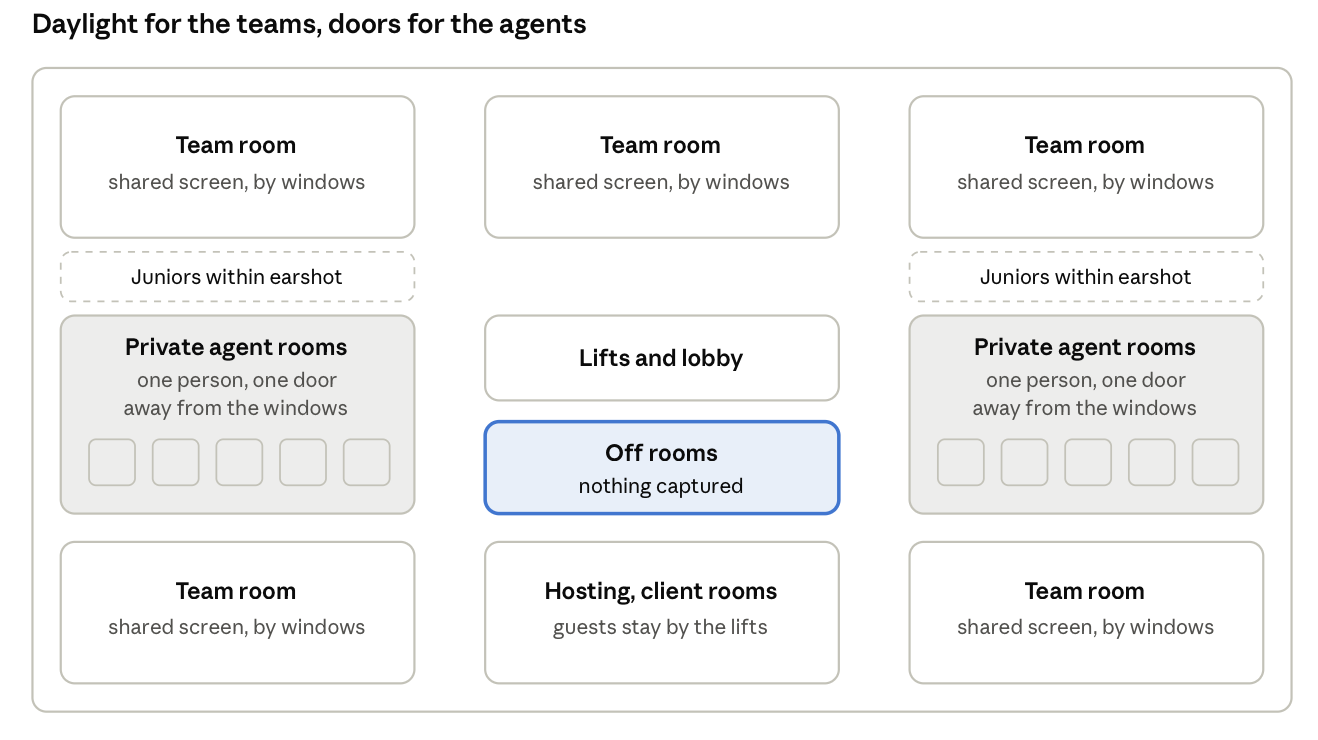
Daylight for the teams, doors for the agents. Team rooms and hosting space should take the windows, because that’s where people spend time together. The small private rooms for working with agents can go in the middle of the floor. People use them in short, focused stretches, on their own, so a door and good sound insulation matter far more than a view. For once, a deep floor with lots of space far from the windows is an asset. If you own one, that’s good news.
Private rooms right next to the team rooms. Her day ran: review with the team, work alone with her agents, review again. The walk between the two should take seconds, so the private rooms should cluster around each team room. A quiet zone at the far end of the floor is too far away.
Off rooms and hosting by the lifts. Guests should be able to arrive, negotiate and leave without walking through anyone’s team space. Putting the off rooms by the lifts also makes them neutral ground, which matters when the person across the table works for another company.
Juniors within earshot. People learn their profession partly by overhearing it. Junior seats belong on the edge of the team rooms and on the route between team rooms and private rooms, where they see and hear how decisions get made. Tucking the graduates away at the far end of the floor defeats the point.
This is a diagram of what sits next to what, so it leaves out circulation and access. Team rooms and hosting take the windows, private rooms for working with agents sit in the middle beside the team rooms, juniors sit between the two, and the off rooms sit by the lifts.
The same logic works for the whole building. Shared floors, hosting and the busiest meeting rooms go low down, near the entrance, where people from different companies cross paths. Each company’s own floors go above. And the software and agents that run the building day to day stay out of sight.
WHAT I GOT RIGHT, AND WRONG
Two years ago I tried to describe some of this in Real Estate as Maven. A maven is an expert who guides you to what you need. The idea was that buildings should do the same: actively help the people in them to work, learn and connect, going well beyond providing space. The usual criticism was that it asked far too much of a building. So how has it held up?
What I got right. The direction. The best of the market is moving from space as a product to space as a service, judged on what it does for the people using it. I also argued that people and AI would end up working intertwined, with no neat split where people do some tasks and machines do others. That’s how teams and their agents now work. And building learning into the building, and running it more like a hotel, both look more right now than they did then.
The worry that has grown. Maven warned that AI would pull people’s thinking towards sameness. The evidence since makes that a credible concern, if an unsettled one. A 2026 study of 68 AI models from 12 companies found their answers to open creative questions grew more alike with each new generation (Patel, Crossman, Aggarwal and Wenger), and a 2025 study of more than 70 models found a similar pattern (Jiang et al., NeurIPS 2025). A September 2026 paper argues that evidence is weaker than claimed (Schaeffer et al.). And technique helps: asking a model for several answers, each with how likely it thinks it is, brings its variety back to about two-thirds of the level it had before its final stage of training (Zhang et al.). The researchers are still arguing. But most people, in most firms, use the same handful of tools on their default settings, which is where the risk is greatest.
What I got wrong. I designed for the wrong unit. Maven imagined one company’s office delivering a long list of services just for that company. And its signature idea was a room that listened to a team and nudged it towards fresh thinking with changes of light and imagery. Looking back, I was over-egging it. If everyone in the room uses the same AI and shares the same company context, no amount of mood lighting brings in new perspectives. People from other companies do. And one company on its own could never afford that long list of services anyway.
Right direction, right worry, wrong unit.
Which brings us to the building.
WHY ONE COMPANY CAN’T FILL THE ROOMS
The economics come down to sharing. Most companies simply don’t have enough moments that need a room to keep good rooms busy. Many companies together can.
Take an illustrative deal room. If your firm needs it one day a week, you use it 20% of the working week and pay for it all week. Share it between five firms and, in principle, it’s in use most of the time. Hotels and airlines have run on this logic for decades. Offices got away with ignoring it, because daily attendance hid the waste.
There’s a catch, and it’s in her diary. She came in on a Tuesday, and so does everyone else. If five firms all want the deal room on Tuesday afternoon, sharing gives you a queue, not a full room. So sharing only pays if someone actively manages demand: charging more at the peak, giving priority to members who commit to more, running events and training on the quiet days, keeping some overflow space, and bringing in occupiers and uses with different rhythms. Managing a scarce peak is the operator’s real job, and the reason it can charge for it.
Get that right and the case for buildings shared by many companies and many uses rests on five things:
Fuller rooms. Many companies’ occasional demand, managed well, keeps the meeting floors, off rooms and learning spaces busier than any one company could.
Costs spread thin. Rooms that can’t record, hosting kitchens, room technology, training programmes and a capable team are largely fixed costs. Shared across dozens of companies, the cost to each falls to something it can justify. For a single small or mid-sized company it’s too much, which is the honest answer to the criticism of Maven.
Smaller firms, and more of them. If AI means firms can do more with fewer people, each needs less space, and a building needs more occupiers to fill it.
Different uses, busy at different times. Offices are busiest midweek, in the middle of the day. Hosting and events peak in the evening. Hotels, gyms, clinics, homes and education are busy at other times again. Mixing them is one of the main ways to spread the load beyond Tuesday.
Access to other people. Meeting people from other companies becomes part of what you’re paying for.
None of this is new in form. ‘Vertical village’ is the phrase used for towers that stack many occupiers around shared space, and London’s King’s Cross shows the same mix of occupiers and uses across a whole estate. What changes is what the shared space is for: less food hall and gym, more of the purposes in the brief.
I’ll call whoever runs it the operator: the people who book and prepare the rooms, guarantee the off rooms, host guests and make introductions. It might be the landlord, or a specialist the landlord hires. Confidentiality is handled by zone. Each company’s own floors are private, the shared floors have clear rules, and the operator guarantees the off rooms, because tenants will trust a neutral operator more than each other.
The case is strongest for small and mid-sized firms buying access to rooms and services they could never provide efficiently themselves. Very large occupiers, and firms whose security, intellectual property or brand demand it, will still want buildings of their own. The shared building sets the benchmark for the top of the market, and plenty of other models will sit alongside it.
WHO CAPTURES THE VALUE
I coined the term Space as a Service in 2013, and this is the clearest version of it I’ve seen. If you own offices, though, this is the uncomfortable bit. Showing that a building like this creates value is one thing. Saying who gets paid for it is another.
The question to ask is: who can charge for the benefit, and who has to fund delivering it? A good operator could raise your rents and keep your tenants longer while earning only modest fees. Or it could own the relationship with occupiers and take most of the margin, leaving you with steady rent and the cost of the building. Which way it goes depends on the contracts, on who carries the costs and risks, and on who occupiers would follow if they moved.
Landlords have three broad choices:
Become the operator. The biggest prize, and the hardest. Running hospitality-grade operations is a different business, with different people, and few landlords do it today.
Partner with an operator. Hotels have split ownership from operation for decades through management agreements, and the terms decide who carries the risk and who takes the upside.
Stay a long-lease landlord. Safest in the short term, and increasingly exposed as occupiers come in for particular moments and stop coming in every day.
If AI agents end up booking rooms for their teams, the booking may happen through the employer’s own systems and bypass the building’s altogether. Owning that booking moment gives you distribution. Whether it also gives you loyalty depends on who delivers the experience.
Then there’s valuation. Valuers reward long, contracted rent over income from running a building, and they’ve good reason to, because that income is less certain. The burden is on the industry to show it lasts and makes money after costs. Until it does, capital will keep favouring the buildings it already knows how to value.
TOO DEMANDING, UNTIL NOW
Maven was too demanding for one company and too early for the technology. For a building shared by many occupiers in the best locations, neither holds as strongly. Three things have moved since 2024, and three haven’t.
What has moved:
The cost of service. AI agents can increasingly handle bookings, room preparation, access and routine requests, so a building heavy on service no longer needs a payroll to match.
Rooms that prepare themselves. The building blocks exist, as the brief shows. What remains is joining them up.
Demand for the best space. Grade A vacancy in City of London towers is around 2% (Barbour ABI), and Grade A made up 92% of Central London take-up in the first quarter of 2026 (Savills). Occupiers are clearly paying for the best existing space. Whether they’ll pay for the package I’m describing is the commercial hypothesis to test.
What hasn’t:
Operator talent. Few landlords run hospitality-grade operations, and the skills are scarce.
Building data. Building systems still don’t talk to each other well, which gets in the way of running a building as one service.
Leases and valuation. Capital still prefers long, contracted income.
The timing matters. Barbour ABI expects new office construction in the UK to recover visibly from 2028, because refurbishment alone cannot meet the shortage of Grade A space. Buildings designed in 2027 and 2028 will open in the early 2030s. They’re the first that can be designed around this brief from the start, and it’s my belief that whoever gets one right sets the benchmark for the decade after.
WHAT WOULD PROVE ME WRONG
Views should come with the conditions that would break them. Some things would show this thesis is wrong. Others would only slow things down.
What would show I’m wrong:
Trusted remote presence. If tamper-proof, verified remote presence arrives and people trust it for high-stakes commitments, ‘presence is proof’ weakens. This is the signpost I watch most closely.
Nobody pays for the package. If occupiers want prime space but won’t pay for off rooms, introductions and learning programmes, the shared building is just a nicer office.
AI becoming more varied. If AI models start giving genuinely varied answers by default, the variety argument goes, and the other three reasons carry the weight alone.
What would slow it down:
Recording obligations. Some regulated firms must record certain communications, which could limit off rooms for exactly the occupiers who would pay most for them.
Confidentiality between rivals. If law and finance firms won’t share floors with competitors, the market is smaller.
Capital not adapting. If income from running buildings stays hard to value, owners will keep building what lenders and valuers already understand.
THE ROOM IS THE POINT
The office of the AI age is smaller for each company, busier in each room, and shared by far more companies. It’s run as a service, built around the moments when people commit, decide and learn from each other, and designed by people who start at the right end.
Two years ago I said real estate had to become more than real estate. It still does. The difference is that now we can see what it has to become, and why. Whether you own, design or occupy offices, that’s your brief.
Design for the moments that need a room. Let the agents have the rest.
We Built the Tool. What’s Left for the Human?
A bespoke commercial real estate strategy tool, built with AI in two rounds totalling 78 minutes. And the human adds...?
Asset Strategy Lab: a synthetic office asset, three strategies, editable assumptions and guided interrogation. Built with AI in two rounds totalling 78 minutes.
This morning I asked Codex to build a tool to help an owner compare three options for an office building: sell now, hold with essential works, or refurbish and re-let. Forty-nine minutes later, we had a working demonstration. A second round, taking another 29 minutes, added guided interrogation of the data. By then I was wondering - what, exactly, was left for the human to do?
The tool is called Asset Strategy Lab. It uses an explicitly synthetic UK multi-let office: several tenants, partial vacancy, staggered lease expiries and a refurbishment requirement.
You can change the important assumptions, compare the strategies over a common ten-year horizon, inspect the cash flows, save scenarios and explore where the preferred strategy changes as refurbishment costs, rents and letting delays vary.
The interrogation feature was my idea. Ten questions you would naturally ask of a strategy model: what makes refurbishment worthwhile, how much funding is required, what breaks the ranking, how dependent is the answer on the exit? Select a question and get a calculated answer that updates with the assumptions.
For the busy reader: AI supplied much of the domain specification as well as the software, and subsequently helped challenge the model’s structure. Human questioning improved the work, while some of those questions could now become reusable instructions and tests. The professional opportunity is to build better analytical capability and establish where it deserves to be relied upon. The human contribution needs to be examined repeatedly as capability, evidence access and the surrounding process change.
I posted the demonstration on LinkedIn. Two early comments made sensible points. One asked about the comparable and cost evidence, and whether we had tested it against a real asset. The other emphasised understanding what breaks a ranking, particularly when several adverse assumptions combine.
Quite right.
The asset is synthetic. We checked calculations through a separate implementation within the same AI-assisted project; real-asset testing and independent professional validation remain to be done. And the tool already lets you combine weaker rents, higher costs, longer delays and other changes.
My initial response was that these comments reinforced the point. If we can build the calculations this easily, we can spend more time thinking about the inputs, investigating the property and testing the assumptions. Less spreadsheet wrangling. More attention to what changes the decision.
Which sounds like a promising division of labour.
Then I realised how much I had delegated.
I had outsourced some of the expertise too.
I am not an asset manager. I had supplied the purpose, the three strategies and the kind of experience I wanted a professional to have. Much of the detailed specification came from the AI: how lease events, income, incentives, works, operating costs and disposal proceeds would be represented.
An experienced asset manager might have briefed it better. They might have demanded renewal pathways, distinguished expiry from vacant possession, or challenged the exit convention immediately. We have yet to test what their contribution would have improved.
But the AI could already explain why these things mattered. Like it or not the model, suitably steered, would specify the product as well as any human.
The test is whether the relevant knowledge does get into the assignment, implemented appropriately and checked. Knowing an issue exists and reliably dealing with it are separate achievements. Both humans and AI can fall short.
Our next conversation therefore moved beyond the numbers entered into the tool. We started examining the model itself.
Changing only the refurbishment letting delay, while keeping the other default assumptions, produced these results:
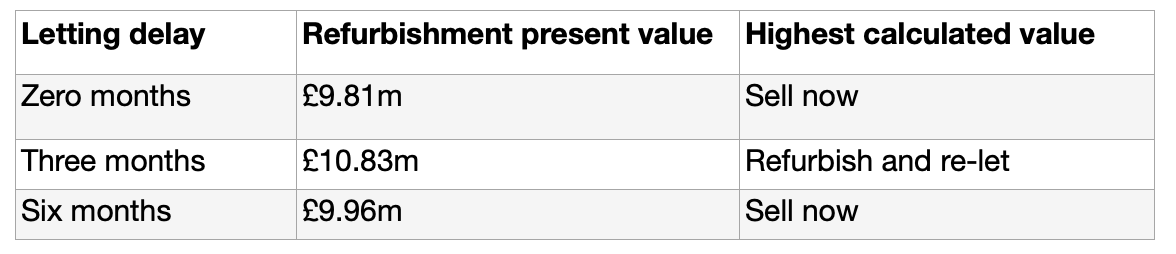
The net proceeds from selling now were £10.64m in each case. All figures are rounded outputs from the synthetic model.
Why would taking longer to let improve the refurbishment result?
The delay moves subsequent lease expiries and rent-free periods. That changes the income falling into Year 11, which the model capitalises to estimate the exit price. At three months, the higher calculated exit value more than offsets the reduction in cash received during ownership.
The arithmetic follows the chosen rules. The economic question is whether a purchaser would value that temporary income pattern in the same way, or assess the longer income stream differently. Before relying on the result for a real asset, we would want to test alternative exit treatments.
This distinction matters: correct calculation, adequate representation of the asset, and fitness for the owner’s decision are three separate requirements.
Lease pathways deserve the same scrutiny. RICS’ DCF guidance discusses breaks, renewals and new lettings, and cautions against blanket assumptions that every tenant stays or leaves without supporting evidence. Adjusting the rent cannot compensate for a consequential pathway that the model omits.
The next tempting conclusion would be that the human supplies the economic understanding. Except the AI helped identify and explain this issue too.
My contribution was to keep reopening the question.
Could the tool be better? Should the AI have identified these choices earlier? What would a sceptical professional challenge? And why was it assigning something to the human when it could apparently help do that work itself?
I could demand a better examination before I knew precisely what that examination should contain. The AI supplied much of the detail.
That is a useful form of collaboration. You can direct, challenge and persist without personally possessing every piece of expertise the task requires. It also puts a responsibility on the system: it should surface consequential questions reliably, before the user has to discover what was missed.
Repeated prodding is an imperfect process. It can produce improvements, unnecessary features or another afternoon down a rabbit hole. Better means better suited to the decision, with sufficient evidence to justify reliance. A larger tool can simply contain more ways to go wrong.
Nor can we cover every possible challenge. We can aim to handle material foreseeable cases, expose consequential assumptions and recognise when the current model is inadequate. Complexity belongs in the engine room; clarity belongs in the investment committee. The user should be able to interrogate the moving parts when it matters.
Once we discover a productive challenge, however, we can retain it. A build instruction can require scrutiny of lease pathways. A model can offer alternative exit treatments. A test can preserve the surprising delay example and demand an explanation when a new version behaves differently.
The next user benefits without repeating my questions.
Some of today’s human intervention becomes tomorrow’s process.
This is one way the boundary moves. It can happen through better instructions, access to evidence and methods of checking, alongside improvements in the underlying models. AI can help construct those improvements as well.
One distinction about the demonstration: AI built the software, while its live calculations and ten interrogation answers follow defined rules. The published app runs a model we can inspect. It does not continuously research the market or independently revise its economic structure. Those would be further capabilities to build and test.
Our conversation nevertheless went beyond what the app currently does. We used AI to question its specification and explore how it could improve. The analytical machinery and some of its criticism were supplied by the same technology.
So what is left for us humans?
For this example, I would look at four contributions.
Purpose and preferences. What does the owner want? Maximum calculated value, liquidity, limited capital exposure, or a particular portfolio outcome? AI can help reveal conflicting objectives and apply an explicit mandate. Those objectives still need an accountable source.
Evidence beyond the system’s current reach. A survey finding, a tenant’s confidential intention, a contractor’s exclusion or a negotiation happening this afternoon. AI can identify why such information matters. Obtaining it may require access, investigation or cooperation that the system currently lacks.
Challenge at the boundary. Recognising that the existing assumptions or scope no longer fit. Perhaps partial refurbishment becomes feasible, or a tenant’s intentions change the possession strategy. Both people and AI can contribute to this challenge. We should examine whether the intervention actually improves the work.
Authority and commitment. How much reliance has the system earned? What may it recommend or execute, within which limits? People and organisations can authorise bounded delegation in advance. Responsibility does not require manually selecting every action.
The distinction between information inside and outside the system’s accessible world is useful. But it leaves plenty of movement: a document connection, better records or authorised investigation can bring previously external evidence within reach.
I would expect the composition of human input to change. Claiming a smooth decline in every workflow would go beyond what we know. Expanded capability can also generate more options, assets and decisions requiring attention.
For a CRE professional, the opportunity could be substantial.
A well-tested tool could make more extensive analysis economical for owners and assets that previously could not justify it. You could examine more opportunities, revisit decisions more frequently and investigate alternatives that a conventional fee or time budget made impractical.
That is my commercial hypothesis. The prototype demonstrates capability creation; the market opportunity and decision quality still need testing.
Some remaining inputs could become more consequential. Knowing that a major tenant intends to leave may overturn the preferred strategy. A strong tool helps you establish that significance quickly and decide what to investigate next.
But information gains value through relevance, credibility and timing. Being unknown to the AI is insufficient. Whether you capture that value also depends on who else can obtain it, the service you provide and the market in which you operate.
There are three separate questions: how many human interventions does each asset require, how consequential are they, and how much work becomes economical to undertake?
Those answers can move in different directions.
And greater analytical capability does not guarantee higher fees or the same number of jobs. Clients may expect more, prices may fall, and value may concentrate elsewhere. An enthusiastic, adaptable professional can deliver excellent work while facing a tougher market.
Alarm is a reasonable response, including for people who are all-in on AI. Scalable tools also make it possible to reproduce a shared modelling weakness across many properties. Expanding coverage requires a corresponding ability to establish quality.
I keep returning to Human Judgement Has a Timestamp. This morning’s exercise gives that argument something tangible: a tool, a set of questions, a structural challenge, and a changing account of what I contributed.
When we say the human ‘wins’, we need to specify the claim.
Performance means the person produces a better analysis, prediction or decision. That needs evidence and reassessment. Preference means someone values human attention or dealing with a person. Authority means an institution assigns people responsibility for objectives and commitments.
Each can sustain human value for different reasons. None tells us how many people will be employed, or what they will be paid.
I would like to discover where humans will always win. I cannot yet give you a defensible list. Creativity, judgement and relationships contain many activities, each requiring examination. Declaring the whole category permanently human would end the investigation just as it becomes useful.
Nor can I attach a credible expiry date to expertise. We can identify what sustains a particular contribution: better demonstrated performance, inaccessible evidence, client preference, institutional authority or a process nobody has redesigned. Then ask what would justify changing the allocation.
For you, three capabilities increasingly belong together: building useful tools, establishing their fitness, and reconsidering where human involvement adds value. The learning includes discovering occasions when the machine needs challenge and occasions when your intervention adds little.
This morning’s experiment has made the question more concrete.
We can now build tools that perform substantial analytical work, answer consequential questions and help us challenge their own assumptions. We can improve them through a conversation, even when we cannot initially specify everything that improvement requires.
Some of our contributions will become part of the software. Others will remain valuable because they bring evidence the system cannot obtain, express the interests it should serve, or secure the cooperation needed to act. We need to keep examining which is which.
That uncertainty is unsettling, including for those of us enthusiastic about AI.
But we can investigate it through the work itself: build, challenge, test against reality, and reconsider the allocation. Human judgement has a timestamp. Our understanding of what we can accomplish with these systems needs one too.